Property income
Net operating income, debt-service coverage, lease terms, tenant quality, vacancy and realistic operating expenses.
COMMERCIAL MORTGAGES
Akali Capital helps business owners, investors and developers finance commercial real estate with a strategy built around the property, its cash flow and the borrower’s larger objectives—not a one-size-fits-all product.
STRATEGIC FINANCING ADVICE
Commercial mortgage approval depends on how the complete transaction is understood and presented. We organize the financial story, identify the most suitable lenders and negotiate the structure from initial review through closing.
That may mean a conventional bank or credit union for long-term pricing, an alternative lender for flexibility, or a private facility when speed and certainty are more important. The goal is a financing structure that fits the property and the business plan.
HOW LENDERS REVIEW THE FILE
Every lender has different policy, but a strong request answers the important credit questions before they become obstacles.
Net operating income, debt-service coverage, lease terms, tenant quality, vacancy and realistic operating expenses.
Credit, liquidity, net worth, business performance, ownership experience and support available outside the property.
Current appraisal, property condition, market demand and the relationship between the loan request and sustainable value.
Purchase, refinance, renewal, capital improvement, equity release or a bridge to a defined longer-term outcome.
RECENT MANDATE
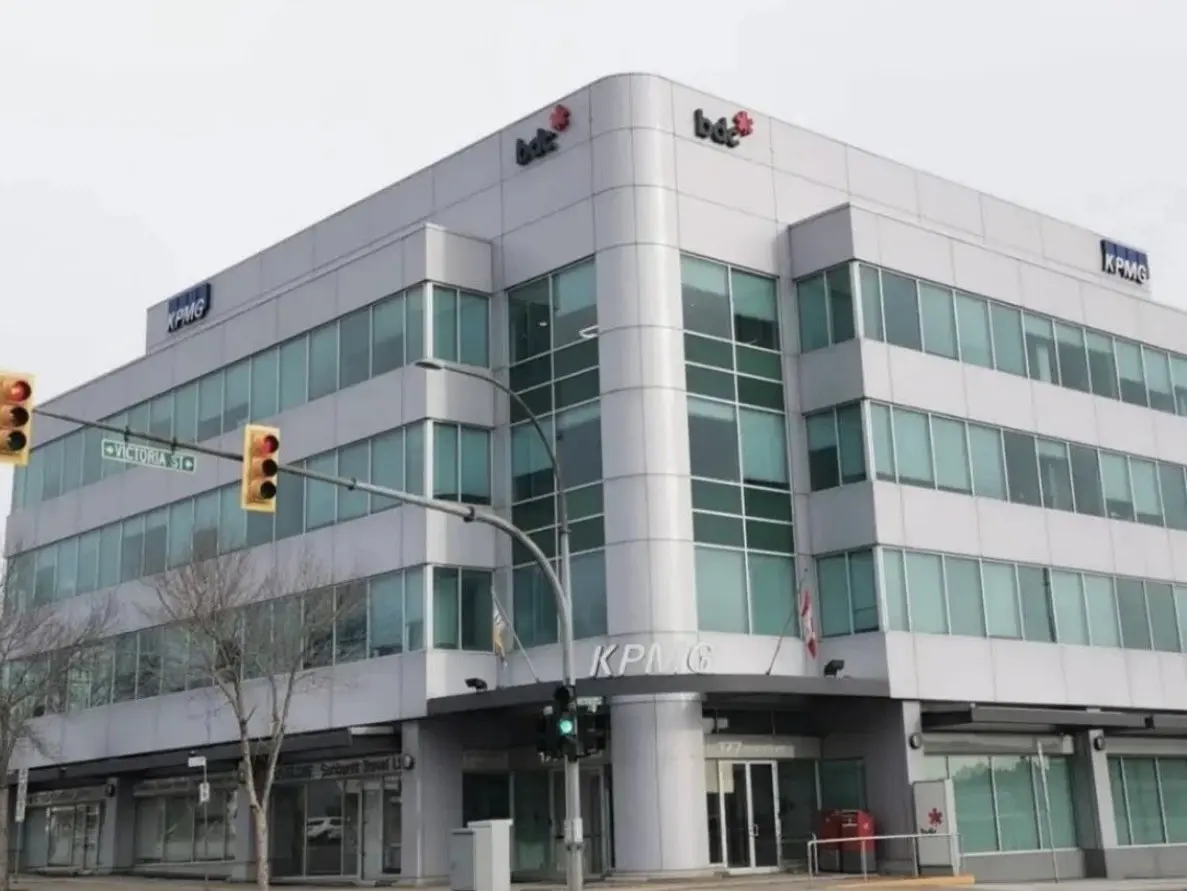
Conventional acquisition financing was completed on a short timeline with maximum leverage and a long amortization designed to support ongoing cash flow.
5-year term • 25-year amortization • Prince George, BCPast transaction details are examples only. Financing terms depend on lender approval and the circumstances of each request.COMMON QUESTIONS
Common property types include industrial, retail, office, mixed-use, hospitality, multifamily and owner-occupied business premises. Specialized properties may require a more targeted lender strategy.
Potentially. Available equity depends on current value, sustainable property or business cash flow, existing debt, borrower strength and the intended use of proceeds.
A broker can identify suitable lenders, package the request for credit review, compare structures and coordinate appraisal, legal and closing requirements. This can be particularly valuable for time-sensitive or non-standard transactions.
START A CONVERSATION
Speak directly with Gary about the property, timing and financing objective. There is no obligation for an initial discussion.