Property equity
Current appraised value, existing mortgages, property condition and the lender’s acceptable loan-to-value range.
PRIVATE MORTGAGE FINANCING
Private financing can create time and flexibility when a conventional lender cannot meet the borrower’s deadline, property type or credit circumstances. Akali Capital helps clients compare private mortgage options, understand the full cost and build a realistic exit before committing.
STRATEGIC FINANCING ADVICE
A private mortgage is often most useful as a bridge: to close a purchase, complete construction, resolve title or tax issues, consolidate urgent obligations, protect an existing investment or create time for a conventional refinance.
The lowest stated rate is not always the best result. Advance amount, lender and brokerage fees, interest calculation, repayment flexibility, legal costs, extension rights and discharge terms all matter. We compare the complete structure and explain the trade-offs in plain language.
HOW LENDERS REVIEW THE FILE
Every lender has different policy, but a strong request answers the important credit questions before they become obstacles.
Current appraised value, existing mortgages, property condition and the lender’s acceptable loan-to-value range.
A clear explanation of what the new capital will accomplish and why the request is time-sensitive or outside conventional policy.
Sale, refinance, construction completion, incoming receivables or another credible and time-bound source of repayment.
Credit history, income or liquidity, property taxes, insurance, liens and any title matters that must be addressed.
RECENT MANDATE
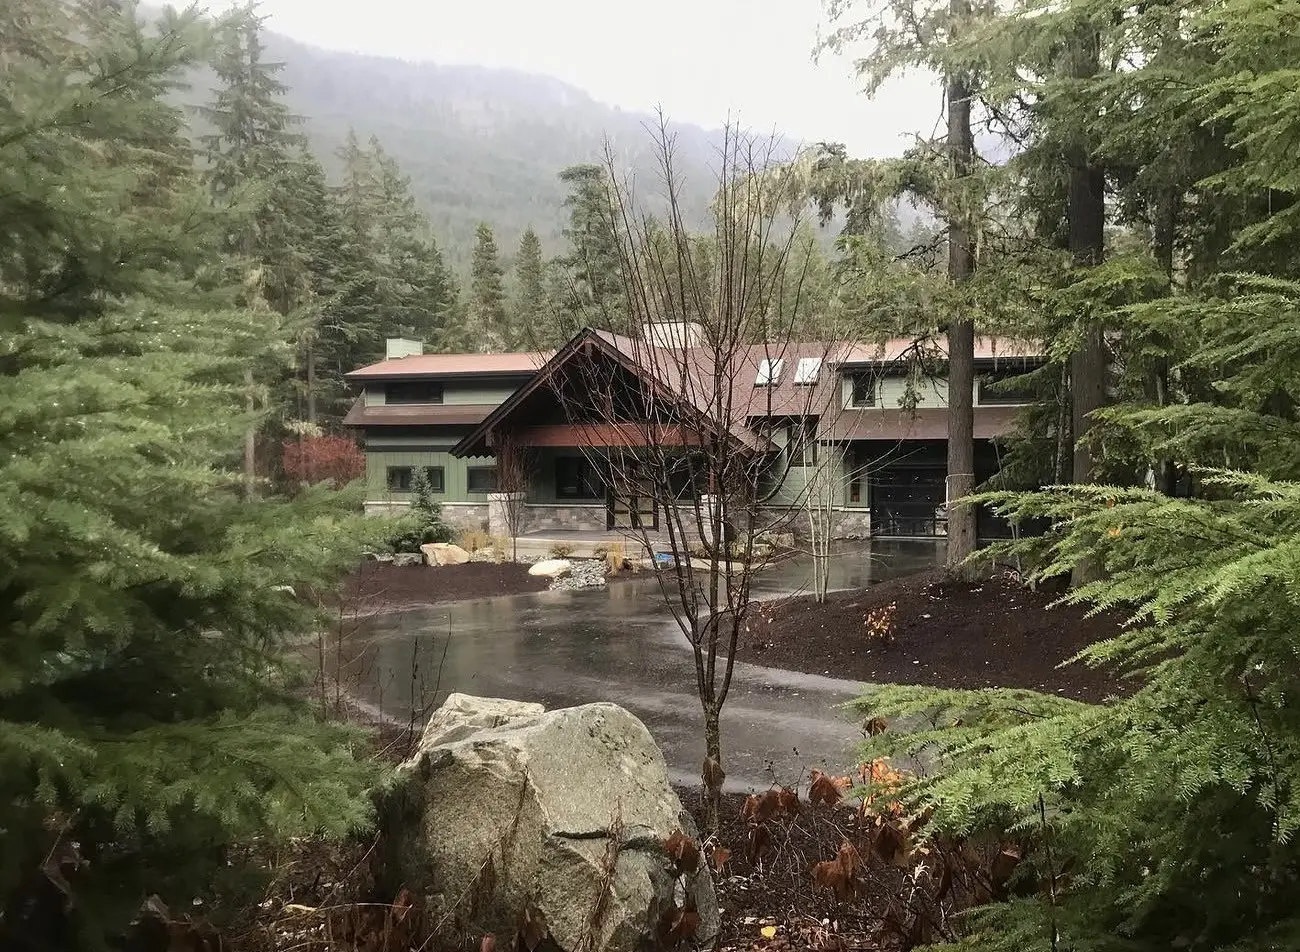
A complex refinancing addressed existing private debt, outstanding obligations and title complications, giving the client time to protect the substantial capital already invested in a luxury home project.
New first mortgage • time-sensitive • Whistler, BCPast transaction details are examples only. Financing terms depend on lender approval and the circumstances of each request.COMMON QUESTIONS
It may be appropriate when speed, property equity or flexibility matters more than conventional pricing, provided the borrower has a realistic repayment plan and understands the complete cost.
Potentially. The lender will review the combined balance of the first and proposed second mortgage against current property value, along with title, taxes, insurance and the repayment strategy.
Timing depends on the appraisal, title, borrower documents, lender due diligence and legal work. Well-organized requests can move faster than conventional financing, but no closing timeline is guaranteed.
START A CONVERSATION
Speak directly with Gary about the property, timing and financing objective. There is no obligation for an initial discussion.