Rental economics
Supportable rents, vacancy, expenses, net operating income and debt-service coverage under lender assumptions.
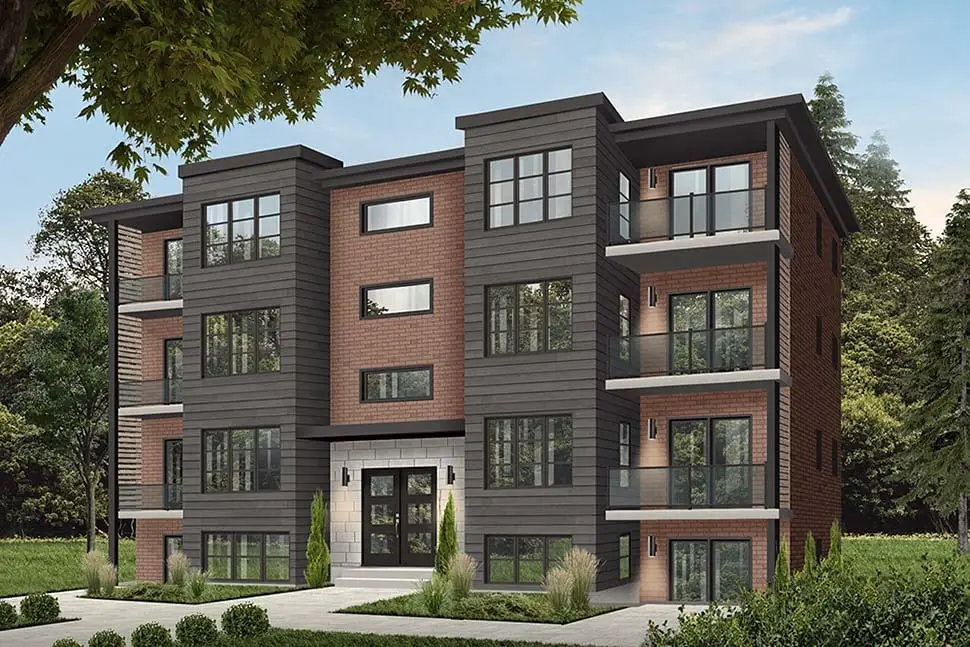
MULTIFAMILY & CMHC FINANCING
Purpose-built rental and apartment financing requires careful coordination of construction costs, rents, operating assumptions, borrower experience and long-term debt. Akali Capital helps clients compare conventional and insured strategies and prepare a complete lender-ready submission.
STRATEGIC FINANCING ADVICE
The best multifamily structure considers more than the initial loan. Construction advances, stabilization requirements, lease-up timing, operating expenses and the eventual term facility all affect equity needs and project returns.
We help developers and investors assess conventional financing and CMHC-insured options for qualifying projects. Program rules and lender requirements can change, so each application is reviewed against current underwriting at the time of submission.
HOW LENDERS REVIEW THE FILE
Every lender has different policy, but a strong request answers the important credit questions before they become obstacles.
Supportable rents, vacancy, expenses, net operating income and debt-service coverage under lender assumptions.
Approvals, plans, budget, appraisal, environmental review, consultants and a realistic completion schedule.
Relevant ownership or development experience, liquidity, net worth, guarantees and contingency resources.
Lease-up timing, property management, take-out conditions and the path from construction to long-term debt.
RECENT MANDATE
An insured financing strategy was structured around long-term rental income and the borrower’s development objectives for a new Alberta multifamily property.
Construction and term strategy • AlbertaPast transaction details are examples only. Financing terms depend on lender approval and the circumstances of each request.COMMON QUESTIONS
CMHC-insured options may be available for qualifying purpose-built rental projects. Eligibility, leverage, pricing and amortization depend on the applicable program, lender underwriting and the project’s characteristics at the time of application.
Not always. Some lenders can consider a bridge or staged take-out, while others require defined occupancy and income thresholds. The best approach depends on lease-up progress and the selected term lender.
Potentially. Unit count, property type, borrower experience, zoning, rental income and program requirements determine which residential, commercial or insured financing path applies.
START A CONVERSATION
Speak directly with Gary about the property, timing and financing objective. There is no obligation for an initial discussion.